How Ford Financing Works at a Hazelwood, MO Dealership
The truth about Ford Motor Credit tiers, F&I office mechanics, and credit scores at a Hazelwood, MO Ford dealership — myths corrected, process explained.
Ford financing at a Hazelwood, MO dealership works through a two-track system: the finance and insurance (F&I) office submits your credit application to Ford Motor Credit Company (Ford's captive lender) and to a network of outside banks and credit unions simultaneously, then presents you with the best-qualifying offer. The common myth is that the dealership sets your interest rate. It doesn't. Lenders assign a tier based on your credit profile, and the dealer structures the deal around what those lenders return.
Myth #1: The dealership decides your interest rate — is that true?
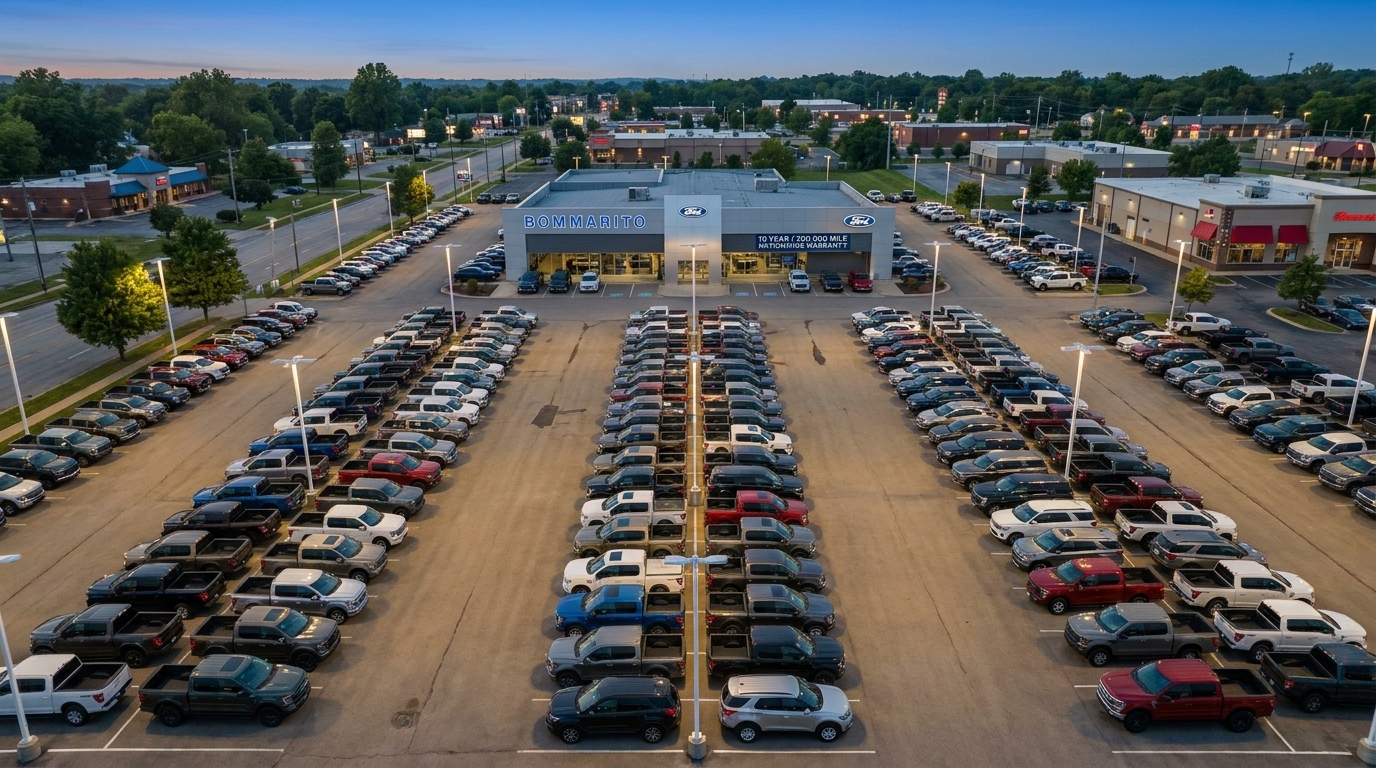
No. The dealership does not set your rate. Ford Motor Credit and outside lenders assign a credit tier based on your FICO score, debt-to-income ratio, and loan-to-value on the vehicle, and that tier determines the rate offered. The F&I office at Bommarito Ford Superstore Hazelwood packages the deal, but the underwriting decision sits with the lender.
What the dealership CAN do is shop your application to multiple lenders at once — something you'd have to do one-by-one on your own. Ford Motor Credit is the captive lender, meaning it exists specifically to finance Ford vehicles and often carries the manufacturer's promotional programs (special APR offers, lease subvention, first-time buyer programs). Outside credit unions and banks compete against those captive offers. Whichever comes back strongest for your profile is what you see on the buyer's order.
Myth #2: You need perfect credit to buy a Ford — what credit score do I need?
There is no minimum credit score required to buy a Ford. Ford Motor Credit approves across a wide range of tiers, from prime (typically 700+) down through subprime, and dealerships like Bommarito Ford Superstore Hazelwood work with secondary lenders for buyers with challenged credit. Your score affects the RATE and terms, not whether financing exists.
Tier assignment is a lender calculation, not a dealer preference. Ford Motor Credit's internal tier grid uses FICO, but also weighs payment history, current debt load, employment stability, and the specific vehicle being financed (new vs. used, model year, mileage). A 620 score on a new F-150 with 20% down looks different to underwriting than a 620 with zero down on a five-year-old used truck. Bring documentation — pay stubs, proof of residence, references — and the F&I office has more to work with.
Myth #3: Ford Motor Credit is always cheaper than a credit union
Not always. Ford Motor Credit wins on manufacturer-subvented promotional rates (the special-APR offers tied to specific models and terms), but credit unions frequently beat Ford Credit on standard-rate loans for prime borrowers. That's why the F&I office shops both. The correct answer depends on the specific offer live for your model, term length, and credit tier the week you buy.
This is where a lot of buyers leave money on the table. Walking in pre-approved from your own bank or credit union isn't a mistake — it's a floor. It gives the dealer a target to beat. If Ford Motor Credit or one of the dealership's outside lenders can beat your pre-approval, you take that. If not, you use your pre-approval. Either way, you win. For current promotional programs on specific models, check the specials page at https://www.bommaritoford.com/.
Myth #4: The F&I office is just paperwork — what actually happens there?
The F&I (finance and insurance) office is where the deal is structured, funded, and finalized. After you agree on a vehicle price, the F&I manager submits your credit application electronically to lenders, receives approvals with specific rate/term combinations, presents financing options, and offers optional products like extended service plans, GAP coverage, and tire-and-wheel protection. This process can take some time depending on the complexity of the deal.
Everything in the F&I office is negotiable or declinable except the vehicle price you already agreed to, sales tax, title, and registration fees. Optional protection products are exactly that — optional. GAP insurance is worth considering if you're financing more than the vehicle is worth (common with low down payments), because Missouri does not require GAP but a total-loss claim without it leaves you owing the difference. Extended warranties make sense for buyers who keep vehicles past the factory bumper-to-bumper and powertrain coverage periods.
Typical Ford financing structure at a Hazelwood dealership
| Element | Who Controls It | Negotiable? |
|---|---|---|
| Vehicle sale price | Dealership / you | Yes |
| Trade-in value | Dealership appraisal | Yes |
| Interest rate (APR) | Ford Motor Credit or outside lender | Rate shopping only |
| Loan term (months) | You, within lender limits | Yes |
| Down payment | You | Yes |
| Missouri sales tax | State of Missouri | No |
| Title & registration | Missouri DOR | No |
| GAP, extended warranty | F&I office (optional) | Yes / decline |
Myth #5: Missouri sales tax works like other states — does trade-in reduce it?
Yes, and this is a genuine advantage Missouri buyers have. Missouri applies state sales tax plus local taxes to the DIFFERENCE between the new vehicle price and your trade-in value, not the full purchase price. Trading in a vehicle reduces the taxable amount — you pay Missouri sales tax only on the difference between the new vehicle price and your trade-in value. St. Louis County adds local sales tax on top of the state rate, and Hazelwood buyers pay based on the address where the vehicle will be registered.
Missouri also gives you a set window from the purchase date to title and pay sales tax at the license bureau — the dealership doesn't collect it at signing the way dealers in some neighboring states do. Budget for it. Missouri's trade-in tax credit rule also lets you apply the sale of a private-party vehicle sold within a qualifying window before or after your Ford purchase toward reducing the taxable amount, which is worth mentioning to the F&I office if it applies.
What Hazelwood buyers should bring to the F&I office in 2026
Bring a valid driver's license, proof of insurance for the new vehicle (Missouri minimums or better), two recent pay stubs, proof of residence (utility bill or lease), and any pre-approval paperwork from your own bank or credit union. If trading in, bring the title (or payoff information if there's a lien), all keys, and the owner's manual. Having documentation ready shortens the F&I appointment substantially.
Buyers in North County — Hazelwood, Florissant, Bridgeton, Ferguson — often coordinate financing around registration at the Missouri License Office. Because Missouri handles titling separately from the dealership, understanding the sales-tax math BEFORE you sign avoids sticker shock at the license bureau 30 days later. The Bommarito Ford Superstore Hazelwood F&I team walks buyers through the estimated tax obligation at signing so there are no surprises.
Frequently Asked Questions
Can I get pre-approved before visiting a Hazelwood Ford dealership?
Yes. You can submit a credit application online through the dealership website before arriving, which lets the F&I office shop lenders and have approvals ready when you walk in. You can also secure pre-approval from your own bank or credit union first — that pre-approval becomes the rate the dealership's lenders have to beat, which almost always works in your favor.
Does Ford Motor Credit finance used vehicles or only new Fords?
Ford Motor Credit finances both new Fords and Ford Certified Pre-Owned vehicles, and will also finance non-certified used vehicles sold at a Ford dealership, including non-Ford brands on the used lot. Rate structures differ — new-vehicle promotional APRs typically don't apply to used inventory, and used-vehicle rates are generally higher because the collateral depreciates faster and the loan-to-value math is tighter.
How long does the Ford financing process take at the dealership?
From credit application submission to signed contract, a straightforward deal can take a meaningful amount of time, with subprime approvals typically requiring more lender back-and-forth. Submitting your application online beforehand cuts this significantly. The vehicle delivery walkthrough adds additional time after financing wraps, so plan on a substantial visit for a first-time purchase at Bommarito Ford Superstore Hazelwood.
What's the difference between Ford leasing and Ford financing?
Financing means you're buying the vehicle with a loan and own it at payoff. Leasing means you're paying for the vehicle's depreciation over a fixed term with mileage limits, and you return it, buy it, or trade it at lease-end. Ford Motor Credit handles both. Leasing typically offers lower monthly payments but no equity buildup; financing builds ownership but higher monthly cost.
Will applying for Ford financing hurt my credit score?
The credit application generates a hard inquiry, which typically drops your FICO by a few points temporarily. However, multiple auto-loan inquiries within a defined shopping window are treated as a single inquiry by major scoring models, so the dealership shopping your application to Ford Motor Credit and several outside lenders on the same day typically counts as one inquiry, not many.
Can I refinance my Ford loan later if rates drop?
Yes. Many buyers who finance at higher rates due to credit challenges refinance after some time once payment history rebuilds their score. Check for any state-specific prepayment language on your contract before signing.
The bottom line for Hazelwood Ford buyers
Ford financing at a dealership is a competitive-bid process, not a fixed menu. Ford Motor Credit and outside lenders compete for your loan based on credit tier, and the F&I office packages what comes back. The myths worth discarding: the dealer doesn't set your rate, you don't need perfect credit to qualify, Ford Credit isn't automatically cheapest, and the F&I office is more than paperwork — it's where the deal is actually built.
Readers in Hazelwood, MO who want to see what their specific credit profile qualifies for on a current Ford can reach Bommarito Ford Superstore Hazelwood at 675 Dunn Rd, Hazelwood, MO 63042, by phone at (314) 895-0600, or through https://www.bommaritoford.com/ to start a credit application and get a real quote before visiting.